 Analysis by Appwee
I judge a banking app less by how polished its screens look than by whether I can understand what is happening to my money and make sensible choices without feeling rushed. That is the lens I bring to Varo Bank: Online Banking. It is a finance app from Varo Bank, N.A., aimed at people who want to handle routine banking on a phone and may value access to pay earlier or a cash advance. Those are useful possibilities, but I would treat them as tools for specific situations, not a substitute for a plan that makes regular expenses affordable.
Trust is a practical question here, not a feeling created by a tidy interface. Opening a bank account involves sharing sensitive personal information, and using an app for everyday finances means checking balances and transactions in a place you can access quickly. I would take the time to read each screen during setup, understand what information is being requested, and use only a device I can keep secure. A smooth sign-up is convenient; it should not mean clicking through financial decisions without understanding them.
What to check before relying on it
The first useful test is whether the app suits the way you already manage money. If you mainly need a phone-based place to check account activity and receive income, Varo may fit that routine. If your finances depend on features or account arrangements you already use elsewhere, compare those needs before moving your main banking. I would start with the everyday tasks I need to complete, rather than assuming that any app described as banking will replace every part of my existing setup.
Its rating averages 4.6 from around 244,000 ratings, and it has more than 5 million installs. That suggests many people have tried it, but those figures do not tell me whether it fits a particular person’s situation or how support will handle an individual problem. I use popularity as context, not a promise. The app is free to download and rated for Everyone; neither point should be confused with a guarantee that every possible service, transaction, or financial decision has no cost or condition.
Using pay access with a plan
Early access to pay can be helpful when timing is the problem—for example, when a paycheck arrives after a bill is due but the money is already earned. I would still check the dates and amounts involved and avoid building a monthly budget around getting income earlier than expected. A cash advance can also be tempting when a shortfall appears, but borrowing to cover a recurring gap can push that problem into the next pay period. I see these options as a possible bridge, not extra income.
One practical approach is to keep a small buffer in mind before using an advance: list the upcoming bills, the next expected income, and what will remain after both. If the next pay cycle would leave too little for essentials, waiting or looking for a different solution may be safer. The most helpful app is not necessarily the one that makes money available fastest; it is the one that lets me make a choice with a clear view of the consequences.
Small choices that can make the routine easier
If you use a savings feature such as rounding up purchases, I would treat it as a supplement rather than a savings target by itself. Small transfers can build a habit, but they can also reduce the amount available for a near-term bill. I would check the account balance after setting any automatic movement and pause or adjust the habit when cash is tight. Automation is useful when it reflects a decision you have already made; it is less useful when it quietly creates a shortage.
More From Our Writers

OTR Makes Off-Road Roaming a Perfect Fit for Short Play Sessions

Prime Video vs. Netflix and Disney+: More Choice, More Clutter

SHAREit Review: A Fast, No-Cloud Way to Move Files

Cryptoguru Makes Crypto Trading Safer, but Can It Teach Restraint?

FC Mobile 26 Turns Soccer into a Season-Long Service

Reddit Is Worth Your Time Only If You Choose Your Communities
The same care applies to transaction categories and spending summaries. They can help me notice patterns, such as frequent small purchases adding up, but I would not treat a category label as a complete budget or financial diagnosis. A good workflow is to review the activity, identify one change that is realistic, and then check again later. That turns a list of transactions into a decision without encouraging me to overreact to one unusual week.
Getting started and everyday use
When a banking app asks for identity details, the key question is not simply how quickly I can finish. I want to know what I am agreeing to at each step and whether I am comfortable entering personal information on the device I am using. I would avoid signing up over an unsecured public connection, keep my phone’s screen lock active, and make sure I can access the contact details tied to the account. Those are sensible habits for any mobile bank, including this one.
Setup, access, and the everyday routine
First things first, getting started with Varo Bank: Online Banking is a breeze. I downloaded the app from the Play Store and was pleasantly surprised by how seamless the setup process was. They don’t bombard you with endless forms; instead, it’s a quick and straightforward experience. You’ll need your ID, a selfie (yes, you’re reading that right!), and a few personal details to set up your account. It’s designed to be hassle-free, and I found myself up and running in less than 10 minutes.
The interface of Varo Bank is super clean and intuitive. You don’t have to be a tech wizard to navigate it. Everything is laid out in a way that makes sense, and the app’s design is visually appealing without being overwhelming. I really appreciate that they’ve kept it straightforward, focusing on what matters: your money!
Within the app, you can check your balance, view transactions, and manage your finances with just a few taps. It’s also easy to transfer money between accounts or send it to friends and family. They’ve nailed the user experience, making it both newbie-friendly and efficient for seasoned app users.
For a realistic routine, imagine checking your balance before leaving for work, then reviewing a recent purchase when you get home to see how it fits with the rest of the week’s spending. That is a modest but useful role for a banking app: quick visibility and a chance to catch something you do not recognize while it is still fresh in your mind. I would make checking activity part of a regular habit rather than waiting until a bill is due or a balance looks unexpectedly low.
Features, savings, and trade-offs
Now, let's talk about some of the features that really make Varo Bank shine. One of my favorites is the automatic savings tool. You can set it up to round up transactions to the nearest dollar and transfer the difference to your savings. It’s a nifty little feature that helps you save without even thinking about it.
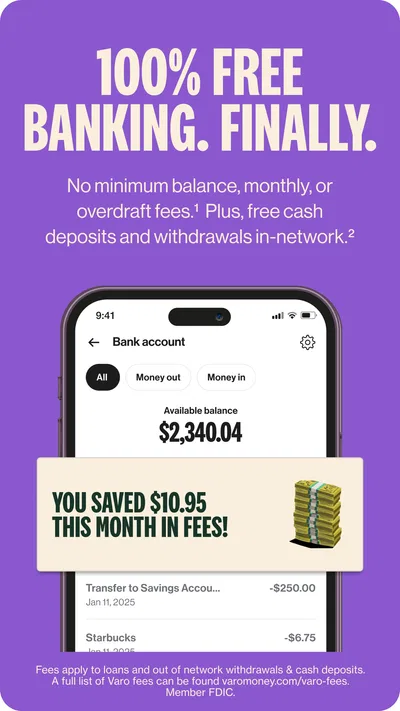
Another cool aspect is the lack of fees. Seriously, none of those pesky monthly maintenance fees! They also offer early direct deposit, which means you get your paycheck up to two days earlier than usual. Who wouldn’t love getting paid early?
Varo also provides a neat budgeting tool that helps you track your spending habits. It categorizes your expenses, so you know exactly where your money is going. It’s like having a personal financial advisor right in your pocket.
I would compare Varo with a conventional bank app by asking what I need most: a familiar branch-based relationship, or a mobile-first routine centered on checking activity and managing money from my phone. Compared with a budgeting-only app, the appeal here is having banking tasks and spending visibility together rather than merely tracking purchases. But people who need in-person help, specialized account services, or a particular feature their current bank already provides should compare those details before switching. Convenience is only an advantage when it covers the jobs you actually have.
One non-obvious trade-off with automatic saving is that a round-up can feel harmless precisely because each transfer is small. If several days of spending are unusually high, those small amounts still come from money that might be needed soon. I would first decide what balance must remain available for essentials, then use automation only if the remaining margin is comfortable. Likewise, spending categories are most useful as prompts to inspect transactions, not as unquestioned proof that every purchase has been classified correctly.
Privacy, controls, and getting help
Security is top-notch, which is essential when dealing with online banking. Varo Bank has all the expected security features, like biometric login, ensuring that your personal data stays safe. I found their customer support to be quite responsive. They offer live chat and phone support if you ever run into issues or have questions. It’s comforting knowing they have your back.
Biometric login can make repeat access easier, but I still think about who can unlock my phone and whether I would notice if it went missing. A phone passcode and careful device access matter alongside a quick sign-in method. When reviewing financial activity, I would check both the transaction amount and merchant details rather than relying on a category alone. If something seems wrong, contacting support promptly is more useful than assuming an unfamiliar label is automatically an error.
For a sensitive action, such as opening an account or reviewing an advance, I would slow down and read the prompts instead of treating the app’s convenience as a reason to move quickly. That is also when I would make sure I am in the genuine app and not responding to an unexpected message asking for account information. These habits do not make a service risk-free, but they keep the user involved in decisions that deserve attention.
Some readers will want to know whether early pay means a guaranteed arrival date, whether every advance is suitable, or whether “no fees” applies to every possible use. I would not build a bill schedule around an assumption: check the terms and timing presented for your own account before relying on either option. The same goes for costs and eligibility. The sensible answer can depend on the specific transaction, so I would read the relevant in-app details rather than treating a broad description as a promise about every circumstance.
Who I would recommend it to
I can see this being a good fit for someone comfortable managing money on a phone who wants a straightforward view of transactions and is interested in building a small savings habit. It may also suit someone whose pay timing occasionally creates a short gap, provided they can assess the impact on the next pay cycle and do not depend on early access every month. The free download lowers the barrier to trying the app, but I would still compare account needs and read the terms before making it the center of my finances.
I would be more cautious if you regularly need to deposit cash in person, rely on branch staff, or want a budgeting system that handles complex household planning. I would also skip using an advance as a routine fix for expenses that exceed income. In those situations, a bank or budgeting setup with the specific support you need—or help addressing the underlying shortfall—may be a better choice than another quick-access feature.
The app is maintained by Varo Bank, N.A., and its current version is 4.24.0, with Android 10 as the minimum operating system requirement. It was released on October 1, 2020, and has 32,000 written reviews alongside its rating count. I mention these details as a way to place the product, not as a shortcut for judging trust: a mature app can still change, so I would keep it updated and review account activity in the same way I would with any bank.
My cautious verdict
All in all, Varo Bank: Online Banking is a solid choice for anyone looking to simplify their financial life. With its user-friendly interface, robust features, and commitment to a fee-free experience, it really stands out from the crowd. Whether you’re a digital banking newbie or a seasoned pro, this app is designed to make managing your money as stress-free as possible.
So, if you’re on the hunt for an online banking solution that’s both reliable and convenient, give Varo Bank a try. It just might change the way you handle your finances for the better!
Varo Bank: Online Banking Pros and Cons
- No monthly fees for basic accounts.
- Early direct deposit feature available.
- Access to free Allpoint ATMs.
- User-friendly interface and design.
- Real-time transaction notifications.
- Limited physical branch access.
- No joint or business accounts.
- Cash deposit options are limited.
- Customer service can be slow.
- Some features require credit check.
Varo Bank: Online Banking Frequently Asked Questions
What features does Varo Bank offer for online banking?
Varo Bank provides a comprehensive suite of online banking features, including no-fee checking accounts, high-yield savings accounts, and early direct deposit. Users can also enjoy budgeting tools, automatic savings features, and the ability to send money instantly to friends and family. Additionally, the app offers 24/7 customer support and robust security measures to keep your information safe.
Is Varo Bank safe to use for online banking?
Yes, Varo Bank is committed to ensuring the security of your banking information. It employs advanced encryption and security technologies to protect user data. Additionally, Varo Bank is FDIC insured, meaning your deposits are protected up to $250,000. Regular updates and security protocols are followed to maintain a secure banking environment.
How does Varo Bank’s fee structure compare to traditional banks?
Varo Bank stands out by offering a no-fee checking account, which means there are no monthly maintenance fees, no overdraft fees, and no foreign transaction fees. This is a significant advantage over many traditional banks, which often charge for these services. Varo also provides free ATM access at over 55,000 Allpoint® ATMs worldwide.
Can I access customer support easily with Varo Bank?
Yes, Varo Bank offers 24/7 customer support to address any issues or questions you may have. You can contact support through the app’s messaging feature, email, or by phone. The customer service team is known for being responsive and helpful, ensuring a smooth experience for users at any time.
What are the eligibility requirements to open a Varo Bank account?
To open a Varo Bank account, you must be at least 18 years old and a U.S. citizen or legal resident. You’ll need to provide a valid Social Security number and a U.S. address. The sign-up process is straightforward and can be completed entirely through the Varo app, making it accessible and convenient for new users.
Gallery